
Welcome to the 1,974 newly Not Boring people who have joined us since our last essay! Join 282,985 smart, curious folks by subscribing here:
Hi friends 👋,
Happy Wednesday!
A consistent theme of this newsletter is that we are fortunate to be living in an Age of Miracles. To whit, I’m sending this over Starlink on a United flight, surrounded by regular people who also received access to free WiFi beamed down from the heavens with their few hundred dollar ticket to fly at 30,000 feet and span the country in mere hours. The Louis CK joke is no longer applicable.
Airlines and internet are a good reminder, though, that a miracle technology does not guarantee a miraculous business. In fact, the more incredible and useful a technology is, and the more you can throw money at scaling it once it works, the more likely it is to attract hordes of competitors who, in aggregate, build too much supply and crash prices.
Let’s get to it.
Today’s Not Boring is brought to you by… Reducto

Meet r-1 mini: High-quality document parsing from $1 per 1,000 pages
AI products get more useful when they can work with more of a customer’s documents. Reducto’s new r-1 mini makes that practical for larger workloads, with pricing starting at $1 per 1,000 pages.
r-1 mini preserves reading order, tables, and layout, so search, extraction, and agents can use the structure of a document alongside its words. Teams can bring historical archives and everyday uploads into their workflows while using r-1 for files where additional accuracy matters.
Reducto already processes more than a billion pages a month for AI teams at Scale AI, Harvey, Toast, and Vanta. If you’re using another parser, apply for up to $5,000 in migration credits and compare the results on your own documents with help from our team.
On Miracles and Moats
It is neither productive nor becoming to call a bubble. Most people who do it are innately pessimistic curmudgeons left out of the fun who believe that the technology underlying the asset in question is overhyped and that those excited about it are rubes. For me, personally, calling a technology bubble would also seem to be pretty off-brand.
Anthropic will probably end its first week of trading at a much higher market cap than it goes out at, and it may well proceed to eat the entire economy en route to becoming the world’s first quadrillion dollar company. The economy very well may end up looking K-shaped in the way that my kids write K’s, with no sense of proportion, a few Anthropic employees at the tippy top each controlling one Bay Area fiefdom/polycule and the rest of us treating Claude with the proper respect in order to continue receiving our allowance from the Machine of Loving Grace (that or somehow outsniping Duet on Kalshi enough to eat).
While I have written that AI is more Oil than God (funny title image choice in retrospect), and I still believe that, it is also true that oil does not produce its own oil, that you can’t replicate Microsoft Office with oil, and that oil is yet to produce a solution to Navier-Stokes.
There is a world in which we look back at Anthropic’s IPO price and laugh at the idea that we ever valued an old school commodity LLM at ~$1.4 trillion. Maybe there’s no new S-curve as intense as coding, because in hindsight, duh, the computers were really good at speaking computer and that didn’t transfer. Or maybe there is, but competition from OpenAI, Google, SpaceXAI, Meta, Chinese open source models, and the neolabs slows revenue growth just enough that compute commitments made in the boom times force the company to sell itself to Amazon or Apple or whoever.
There is another in which Dario has decided that laughing hurts the models’ feelings and well, he’s allowed to tell us not to laugh anymore, since he is the economy. A very real bull case for Anthropic goes something like: it has the best models and they are now improving themselves faster than ever, growing the lead in what may be a winner-take-all market, and unlike other winner-take-all markets, this one extends to all markets, because Anthropic can win whichever markets it chooses to point its smarter-than-anyone models at, from productivity software to medicine to … anything.
Anyone who tells you they know which of those two outcomes will come to pass is full of shit, and I am many things, but I hope not to be full of shit.
There are three arguments against this being a bubble more broadly, though, which are oft-repeated, sound right, and are exactly the things you’d expect to see in a bubble.
Note: I’ll use bubble here as the broad term but I might mean something closer to commodity cycles, and I certainly don’t mean manias, which are when price becomes totally divorced from reality, as with tulips.
The three arguments are:
Unlike other bubbles (lol WebVans and crypto), AI is actually an incredibly useful technology that is being widely and productively adopted in the economy.
These companies are generating real revenue, and growing incredibly fast.
The labs have shown they can be profitable, and any losses are just them investing to capture future growth.
Grant all three! In doing so, however, you’d be saying that the situation is exactly the situation that creates and then deflates bubbles.
A miracle technology arrives.
Early suppliers earn real profits because supply is short.
Demand looks bottomless, which is obvious to everyone in the early numbers.
The demand and profits pull in capital and competitors.
Everyone builds at once, even those who see the glut coming, locking in commitments at scarcity prices just to get capacity online.
Supply arrives, the technology gets better, and prices collapse.
Capital loses, consumers win, and the technology chugs on.
Capital flees, so new entrants can’t get funded.
A survivor or outsider with capital consolidates and becomes the low-cost provider.
Demand catches up, the technology proves bigger than anyone imagined, and the survivor ends up larger than all the failed companies combined.
None of this is new. It’s close to Carlota Perez’s Technological Surge Cycle and Edward Chancellor’s Capital Cycle. Byrne Hobart and Tobias Huber wrote a whole excellent book in praise of bubbles and their role in ending stagnation. What is interesting, though, is that three of the main arguments you hear against AI being a bubble are steps one, two, and three.
The pattern keeps playing out precisely because each new technology really is so impressive that people believe this time, finally, is different.
The first seven steps are pretty consistent, like some law of human nature and capital markets. Steps 8-10 often, but don’t always, play out. Sometimes consumers simply dine on the industry’s corpses.
Take airlines. If ever there was a miracle technology, it was the ability for humans to fly through the air like birds. Flight seemed so improbable beforehand that The New York Times famously predicted it would take 1 million to 10 million years to figure out, just two months and change before the Wright Brothers figured it out.
So did the Wright Brothers get filthy rich? Did those companies that could fly humans through the air like birds become great businesses?
Well, here’s what Warren Buffett had to say on the matter in a 1999 talk at Sun Valley:
“Karl Marx couldn’t have done as much damage to capitalists as Orville did.”
In his 2007 letter, he explained the logic behind the zinger:
The worst sort of business is one that grows rapidly, requires significant capital to engender the growth, and then earns little or no money. Think airlines. Here a durable competitive advantage has proven elusive ever since the days of the Wright Brothers. Indeed, if a farsighted capitalist had been present at Kitty Hawk, he would have done his successors a huge favor by shooting Orville down.
It is unpopular to say it now, perhaps, when everything is moving so fast, but in the long run, a business needs both a product that customers want to buy, and a durable competitive advantage to protect its margins from all of the other companies that want to fulfill those customers’ demands, too. They need moats, and airlines didn’t have them.
Even The Oracle himself, however, couldn’t stay away. In 2016, Berkshire took stakes in American, Delta, Southwest, and United to the tune of roughly $7-8 billion. At Berkshire’s 2017 Annual Meeting, he admitted, “It’s a fiercely competitive industry. The question is whether it’s a suicidally competitive industry, which it used to be.”
He sold all four at a loss in April 2020. He got hit by a Black Swan - COVID - but he pointed to the laws of supply and demand in his decision. “If the business comes back 70 or 80%,” he said, “the aircraft don’t disappear.”
So while not every industry based on a miraculous and broadly useful technology becomes a great industry or produces enduring businesses, they all end up having a bigger impact on the world than anyone could have imagined. Consumers end up winning, and humanity progresses.
There is nothing more optimistic, in fact, than believing that capital will fuel an oversupply of any new miracle technology humans can concoct and in so doing, make the technology cheap enough for everyone to benefit from. Miracles without moats, if you will.
It’s not that capital is stupid, quite the opposite. It takes a pretty spectacular technology indeed to rally the world’s capitalists to invest a significant percentage of global GDP behind a given technology. Oil, railroads, cars, internet. Each of these ended up being even more impactful than their most fervent boosters predicted. In the early days, for example, oil was used to replace whale oil in lamps; it went on to make cars and planes and modern life possible.
And it’s not like those involved don’t see that they might be overinvesting and creating the conditions for their own downfall, but like game theoretically, what are you supposed to do?
The British railways are a great example.
On my birthday, many years before my birth – January 26, 1846 – Charles Russell, chairman of the Great Western Railway, stood in Parliament and urged his colleagues to “expose and discountenance every bubble scheme.” He wanted Britain to slow down the approval of new railways.
In 1842, the first British railroads, including Russell’s, were phenomenal businesses. The Liverpool & Manchester, the London & Birmingham, and a few other early entrants were paying dividends of at least 10%. Great Western, a slightly less good railroad, paid between 6-8%.
Demand for rail transportation seemed bottomless, and there were only so many railways to serve it, at first, when building railroads was hard and prospects were uncertain, but over the next couple of years, entrepreneurs of varying degrees of seriousness introduced hundreds of proposed new railways, each hoping to cash in on those sweet early rail economics.
By the autumn of 1845, Britain was so consumed with railways that the Railway Times spent nine consecutive weeks using its lead article to attack The Times for warning about the speculation in railway shares. On November 17th, The Times published a special supplement tallying the capital required by 1,263 proposed railway schemes. In 1846, Parliament passed acts authorizing 4,540 miles of new track.
Of course Russell wanted to “expose and discountenance every bubble scheme.” Each one brought new competition, which he saw would drive down prices.
Clearly, he was not opposed to railway investment per se, for he himself was playing the game. At an 1848 shareholder meeting in Paddington, he explained why his own railway had taken on such extensive commitments in snatching up rival lines. The Great Western had acted, per The Times, “in self-defence.”
New entrants have nothing to lose and incumbents have everything to lose and both get you to the same place: you have to invest.
That’s how Google is thinking about it today. Founder Larry Page reportedly said, “I’m willing to go bankrupt rather than lose this race.” CEO Sundar Pichai, on the company’s Q2 2024 earnings call, told investors that “the risk of underinvesting is dramatically greater than the risk of overinvesting.”
Zuck agrees. In September 2025, on Alex Heath’s Access podcast, he admitted that “it’s quite possible” that AI is a bubble. “If we end up misspending a couple of hundred billion dollars, I think that that is going to be very unfortunate, obviously,” he added. “But what I’d say is I actually think the risk is higher on the other side. The risk, at least for a company like Meta, is probably in not being aggressive enough rather than being somewhat too aggressive.”
History rhymes.
Earlier this year, Anthropic CEO Dario Amodei told Dwarkesh Patel that he believes a country of geniuses in a data center is coming soon, but that “If you’re off by only a year, you destroy yourselves.” To put a finer point on it, he said, “I could buy a trillion dollars a year of compute that starts at the end of 2027. And if my revenue is not a trillion dollars, if it’s even 800 billion, there’s no force on earth, there’s no hedge on earth that could stop me from going bankrupt if I buy that much compute.”
At the time, Anthropic had committed about $100 billion to compute, a relatively sensible number. Competitors (cough, OpenAI) were being reckless, he thought: “I kind of get the impression that, you know, some of the other companies have not written down the spreadsheet that they don’t really understand the risk they’re taking.” For context, the following week, OpenAI told investors it was targeting about $600 billion in compute spend by 2030, down from a $1.4 trillion number it had previously touted. Whatever, horseshoes and hand grenades.
Anyway, in its S-1, Anthropic reported that it has now committed to $900.9 billion worth of compute through 2045, about half of which is expected before the end of this decade.
This may be the absolute right move! 1. Who am I to say it’s not? 2. Revenue is growing fast. 3. If they don’t, someone else who is less spreadsheet-literate will. 4. They even make their own spreadsheet software now, and 5. This math is likely being run by a combination of incredibly smart humans and models so advanced that they’re too dangerous to release. Plus, Anthropic actually generated an operating profit in Q2 and would have done so again in Q3 excluding roughly $2 billion in noncash donation-matching charges, so they may have their hand firmly on the tiller.
But like, sounds risky, per Dario. And sounds an awful lot like the British railways, then the American railways, even… cannabis?

Thank you Writing Gods. The growers got hit by the same oversupply issue, and now some of them are flying to AI data centers for safety.
Sounds like fiber, too.
We tend to dismiss comparisons between the dot com boom and bust and the AI boom because there were so many obviously dumb, revenue-less companies getting funded and adding dot com to their stodgy businesses’ names and popping 420% that that one was clearly a mania, right?
It’s worth separating the internet stock mania from the bandwidth bubble - overbuilding capacity based on optimistic early demand signals. We look back on it all as silly, but while things got heated, many of those businesses laying fiber were acting rationally, at least independently.
Internet traffic really was exploding. In 1990, basically no one was using the internet. By 1995, 9% of Americans were, and by 2000, 43% were.
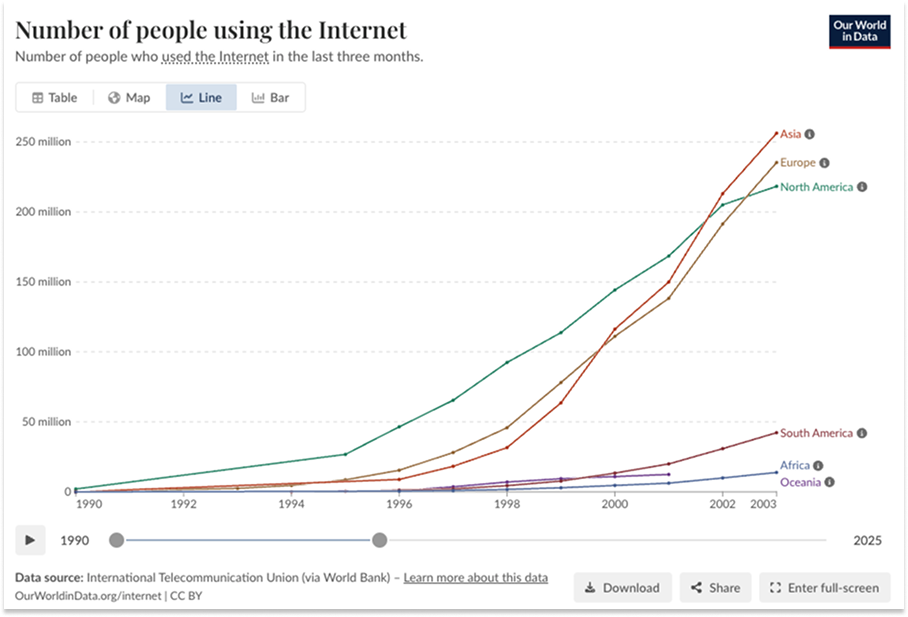
And that was just Americans. The world came online, too, adding new growth S-curves. And that was just the current uses with low-bandwidth internet! I used early dial-up internet. It was painfully slow. It took a minute to get a picture to load, and anywhere from 20 minutes to forever to download a song, assuming someone in your house didn’t get a call. Imagine all of the new use cases that would be unlocked when everyone had access to practically unlimited bandwidth, on-demand. We would watch movies and TV on the internet. We would attend events on the internet. We would do business and buy things and come up with entirely new things to do on the internet once we had the bandwidth.
No less of a luminary than Bill Gates himself made this argument, back in his 1995 book, the #1 New York Times Bestseller, The Road Ahead. And he fucking nailed it. Read that excerpt I just linked. He was totally right, and not even right enough. He wasn’t alone. Qwest Communications, a long-distance fiber optic carrier, made an ad that asked viewers to imagine a motel in which “All rooms have every movie ever made in every language, any time, day or night.” That motel was the internet, baby, and it was available right in your home.
It was hard to imagine where and when demand for the internet would possibly saturate. A 1998 US Commerce Department Report, The Emerging Digital Economy, stated that internet traffic was “doubling every 100 days.” Turns out, it got that number from a 1997 Inktomi white paper, which in turn cited Mike O’Dell, Chief Scientist of bandwidth-seller WorldCom’s UUNET, which, Andrew Odlyzko later figured out was a reference to WorldCom’s buildout pace - supply - and not demand, but no matter! The internet was ripping.
In a 1998 meeting, Qwest CEO Joseph Nacchio responded to an investor question about Qwest and its competitors all laying fiber at once by pointing out that, “The explosive demand driven by the Internet phenomenon ensures there won’t be a glut of bandwidth.”
“If we were even modestly competent executives,” he added, “we’d do well.”
Qwest, which had begun as a division of the Southern Pacific Railroad and laid fiber on the routes the railroad owned, did do well, for a while.
Qwest grew reported revenue from $2.24 billion in 1998 to $3.93 billion in 1999, thanks in part to its June 1998 acquisition of long distance carrier LCI, and its operating profit grew from negative $754 million in 1998 to positive $324 million in 1999. (Well, that and maybe some accounting fraud, per the SEC.) Its market cap rose to $91 billion in 2000. Then it did less well. By August 2002, it had fallen to $1.9 billion.
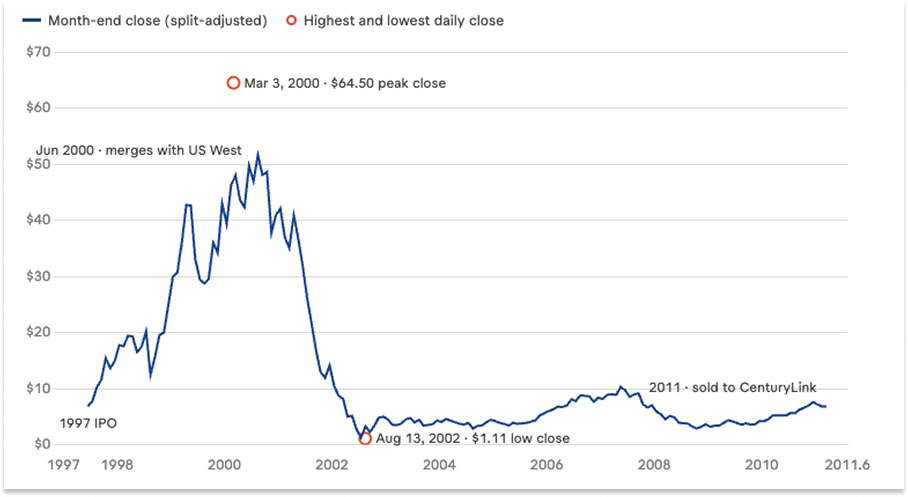
What happened? You’re reading this on the internet right now, from one of the at least two and probably a lot more internet devices that you use nearly all day, that you’re so addicted to, in fact, that you keep trying to stop using them so much.
After growing 10x in 1996, internet traffic really did double frequently – every year! – but it didn’t keep doubling the every 100 days that the broken telephone Commerce report suggested it was.
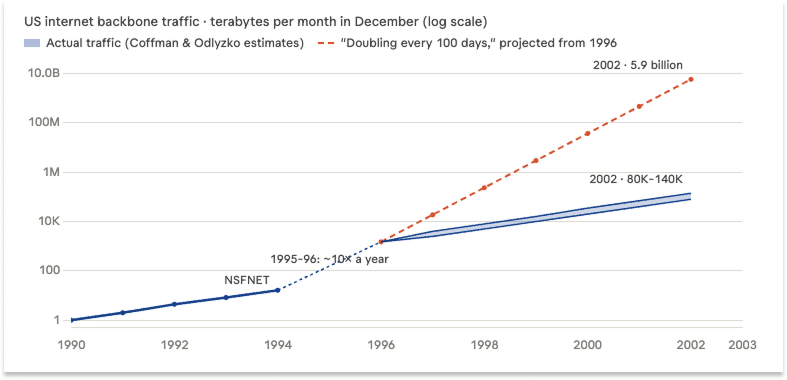
Meanwhile, U.S. long-haul fiber mileage roughly doubled from 1996 to 2001 post the 1996 Telecommunications Act, from 100k miles to 200k miles, while upgrades to the electronics let each strand carry up to 40 times as much data, from 2.5 Gbps to 100 Gbps. In total, telcos spent something like $500 billion on the buildout.
With all that supply, a 2002 TeleGeography report said that bandwidth prices on major U.S. and European routes had fallen about 70% annually for three years. In one example, a 155 Mbps circuit between New York and Los Angeles, a connection that cost $1.8 million a year in 2000 could be leased for under $150,000 by early 2002.
Humanity ended up putting that bandwidth to good use, and needing a lot more, but that was cold comfort to those who’d built out the network. WorldCom filed for Chapter 11 in 2002 amid fraud allegations. Williams Communications filed for Chapter 11 the same year under a $5.9 billion pile of debt. Global Crossing did too, and emerged in late 2003, with its debt load lightened from $11 billion to $200 million. Preferred and common shareholders received nothing.
In the year that Global Crossing emerged from bankruptcy, it had explosive growth. Traffic on its network grew 130%! Problem was, bandwidth wasn’t worth what it once was. Its revenue fell 6%.
The biggest winner – Level 3 – which had raised money at just the right time before the markets shut in February 2000, which had built a cost advantage by laying 12 conduits where others laid one or two, which had the post-crash backing of none other than Warren Buffett, and which rolled up many of its competitors’ corpses at advantageous terms, sold to CenturyLink in 2017 at a price 97% below its peak. Even identifying the eventual winner might not matter if you pay entry prices that assume away the corrosive forces of competition.
But again, what are you going to do? Not play ball? The internet is a fucking miracle. You can chat with anyone in the world, face-to-face, on your computer, or even on a piece of glass in your pocket. Unless you’re a local models guy, you access the country of geniuses in a data center via the internet. You buy things on the internet. You listen to things on the internet. You can watch every movie ever made on the internet, in any language, day or night, and you can even watch a bunch of movies and TV shows that were made specifically because the internet exists and demands more content than even Qwest Communications could ever have hoped the internet would demand. I don’t know what I would be doing without the internet, but it certainly wouldn’t be this. Thank god for the internet.
The fiber companies got a little carried away, sure, but they weren’t idiots. Neither were the people prospecting for oil back in 1860, the year after Colonel Drake (who would end up dying penniless) discovered it in Titusville, PA. Oil was going for $20 a barrel, real money! Problem was, so many people saw that there was black gold in them there hills that the price of a barrel fell to 50 cents by June 1861, and to 10 cents by December, wiping out a ton of prospectors.
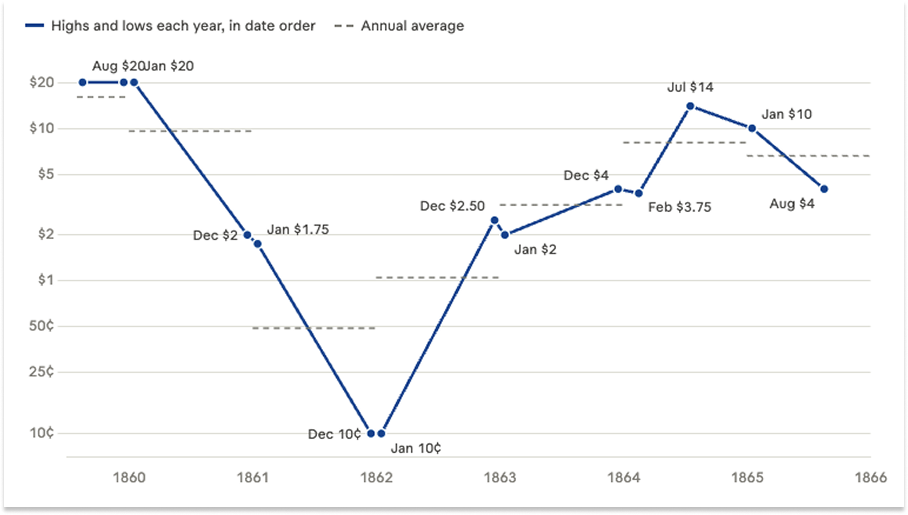
This was not a demand problem, really, although I guess every supply glut is technically a demand problem. Even in the early days, when oil was used only for illumination, demand was practically bottomless. After the gusher-led fall-off in 1861, early wells depleted, demand spiked, and prices rebounded above $8 a barrel in 1864 … which attracted more drillers and an even more frenzied atmosphere.
At Pithole, PA, some once-worthless farmland sold for $1.3 million in July 1865 and resold for $2 million in September. By Christmas 1865, almost 20,000 people lived there. By the Census in 1870, only 237 remained and by 1878, the $2 million farmland was sold back to the county for $4.37.
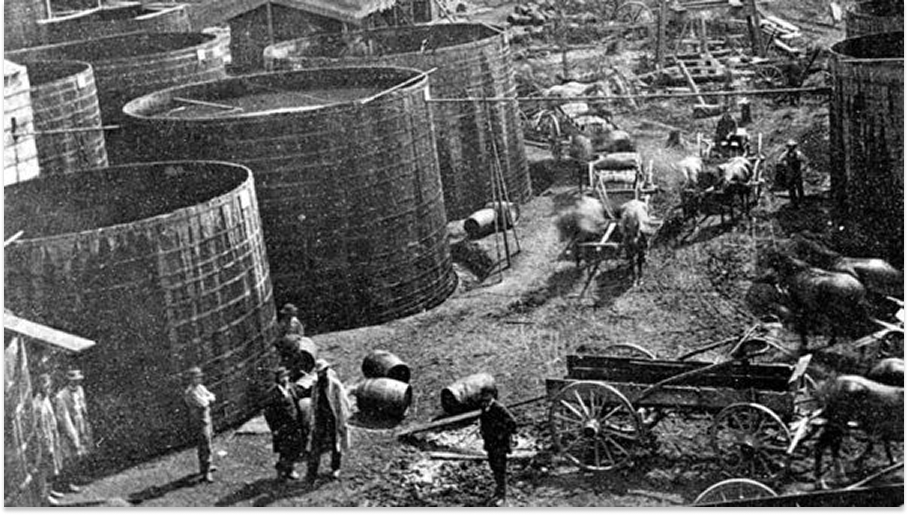
Per PT Barnum (yes, that PT Barnum) in his 1865 Humbugs of the World, roughly 600 petroleum companies sought a combined $500 million of capitalization. “Petroleum exists, no doubt, and is an important addition to our national wealth,” he wrote. “But the petroleum humbug... is a humbug.”
Investors were not wrong on the size of the opportunity. Oil was real, and a single oil company would come to support a market value greater than the entire $500 million.
They got the market sizing right and ignored the competitive dynamics.
John D. Rockefeller did not. The man was too attuned to competitive dynamics, if you believe Ida Tarbell, Theodore Roosevelt, and the US Justice Department.
As we covered in Power in the Age of Intelligence, Rockefeller, who started refining crude in Cleveland in 1863 and would incorporate Standard Oil in 1870, recognized that the constraint to the profitable growth of the oil industry was its volatility, that the way to tamp down on volatility was through scale and control, that to get scale and control, he’d need to drive down costs and capture market share, and that to do that he’d have to improve kerosene yield, sell what others threw away, and aggressively vertically integrate.
By the 1880s, Standard Oil controlled 90% of American refining, which fell to 64% by the time it was broken up in 1911, when its $1.1 billion market cap represented about 6% of the entire US stock market and more than twice the entire industry’s capitalization in 1865.
Where others sought quick profits, Rockefeller sought durable competitive advantage. He won, and consumers certainly won - our world still runs on refined oil to this day - but countless others who totally nailed the scale of the opportunity died in pursuit of it.
Rockefeller was exemplary of the type of entrepreneur who typically comes out of these things on top. He anticipated the glut, and positioned himself to benefit from it.
Whether he’d put it in the same terms, Henry Ford did the same thing. There were something like 2,000 automakers in the first couple decades of the automobile’s existence in America, and from 1900 to 1919, as car ownership grew from roughly 0% to one-third of American households, nearly all of the 2,000 automakers that made those cars failed.
By the early 1940s, when more than half of American households owned a car, just three companies - Ford, GM, and Chrysler – sold 90% of them.
What Ford realized was that in a glut, being the low cost provider of quality, using low prices to get to scale, and using scale to get even lower prices and more scale was how you win.
Cornelius Vanderbilt, who TJ Stiles called “The First Tycoon” and who was the biggest American winner in railroads, didn’t even really care about railroads. His goal was to get as many people and parcels from one place to another as quickly and cheaply as possible, using the best technology available for the job.
Vanderbilt started with sailboats, made a fortune in steamships, and then made a bigger one in railroads. Across the latter two, he looked for routes with advantages in speed and cost. His route to California through Nicaragua was hundreds of miles shorter than the competition’s through Panama, which gave him an advantage so strong they had to buy him out. When the railroad looked like it would be a better way to move things cheaper and faster, he donated his biggest steamship to the Union Navy, got out of shipping, and rolled his capital into rail. But not just any rail - there was plenty of that. He bought the struggling Harlem Railroad, which had valuable access into the heart of Manhattan, reduced its operating costs, then connected it to lines he bought by the Hudson River and then on to Chicago. Amtrak still mostly runs on that same route today, that’s how ideal it was.
Vanderbilt was willing to change technologies, but consistently looked for durable competitive advantages. And while scores of his competitors, who’d rightly recognized that steam and then rail were the future too, lost their shirts, Vanderbilt died with a net worth of about $100 million in 1877, which sounds like a moderately sized seed round, but for context: if he’d sold everything that day, he’d have taken one of every twenty dollars in circulation in America.
Today, Americans have access to relatively cheap flights, logistics, cars, oil, and internet, even if the people who paid in blood, sweat, and capital to make those things abundant didn’t end up surviving. That’s capitalism, baby.
As Yale economist William Nordhaus found in Schumpeterian Profits in the American Economy, “only a miniscule fraction of the social returns from technological advances over the 1948-2001 period was captured by producers, indicating that most of the benefits of technological change are passed on to consumers rather than captured by producers.” He calculated that producers captured only about 2.2% of the total social surplus from innovation, while consumers captured roughly 97–98%. That 97-98% shows up as lower prices, better products, and higher real incomes for consumers rather than as excess profits.
Hell yeah.
A 2004 NBER summary of the paper includes Nordhaus’ interpretation of the recent bust: “Part of the New Economy bubble might have arisen because investors overestimated the appropriability of innovations in that sector.” In other words, it’s not that what was built wasn’t valuable; it’s just that investors overestimated how much of the value they’d be able to capture for themselves.
Plus ça change.
Nearly every promising and ultimately transformational technology goes through this cycle. It’s practically a requirement for being a promising and transformational technology, with a few exceptions.
As I wrote in When to Dig a Moat, startups need to develop moats before they run out of uncertainty. Normally, moats take time to develop, which is why a lot of ultimately successful startups emerge from categories that were highly non-obvious. In categories like oil and AI, the enormous potential demand is obvious to everyone. If you build it, they will come. When demand is near-certain, the only categories that avoided this cycle are ones in which entry was highly regulated like pharma, airlines under federal route regulations pre-1978, Bell Telephone until its patents expired in 1894, or Alcoa with its patented aluminum process. These are Cornered Resources, and when they lapse, competition floods in and the same dynamics play out.
Other edge cases include situations where demand is not certain, like when people don’t realize how good the business is (Amazon didn’t break out AWS profits for nine years, and cloud had killed companies pre-AWS), and when Process Power built on risky bets compounds over decades, as was the case with ASML.
Opportunities where you can’t just throw money at the problem in order to compete, for one reason or another, are somewhat protected. Everything else is subject to the laws of the jungle, and on a long enough timeframe, the jungle favors consumers.
One of the things that investors love about AI is that you can just throw money at it.
It also makes a lot of other things easier to build, which should set this cycle running across industries. Anthropic itself used frontier Claude models to weaken NVIDIA’s CUDA moat so that they and others can more easily… cheat on the world’s largest GPU supplier.


The net of it all is that I think we are entering an age of consumer surplus the likes of which humanity has never seen. We have focused on AI in this piece, but there is a boom underway in sectors from robotics to power to manufacturing to biotech.
Categories that once seemed impossibly sci-fi - from flying cars to robots - are now being pursued by so many smart, well-funded players, that the question seems to no longer be if, but how soon, and who will capture the profits? As we speak, there are companies devising cures for cancer that until recently would have been miraculous, but now get outcompeted by newer technologies within months.
As a human and consumer, I am so psyched to get to live through this Age of Miracles.
As an investor… I think it is simultaneously one of the most fraught and most exciting times to get to invest. There exist companies that, in my opinion, stand to benefit if the boom continues and if there is suddenly a fire sale on miracle technologies.
I like companies that are like Vanderbilt, Rockefeller, or Ford – there will be some bumps, but if a better technology or model becomes available, they can plug it in to deliver a better product more cheaply as opposed to being threatened by it. While the internet thrived on network effects, I suspect scale economies and cost advantages will be critical as technology once again reaches out into the physical world.
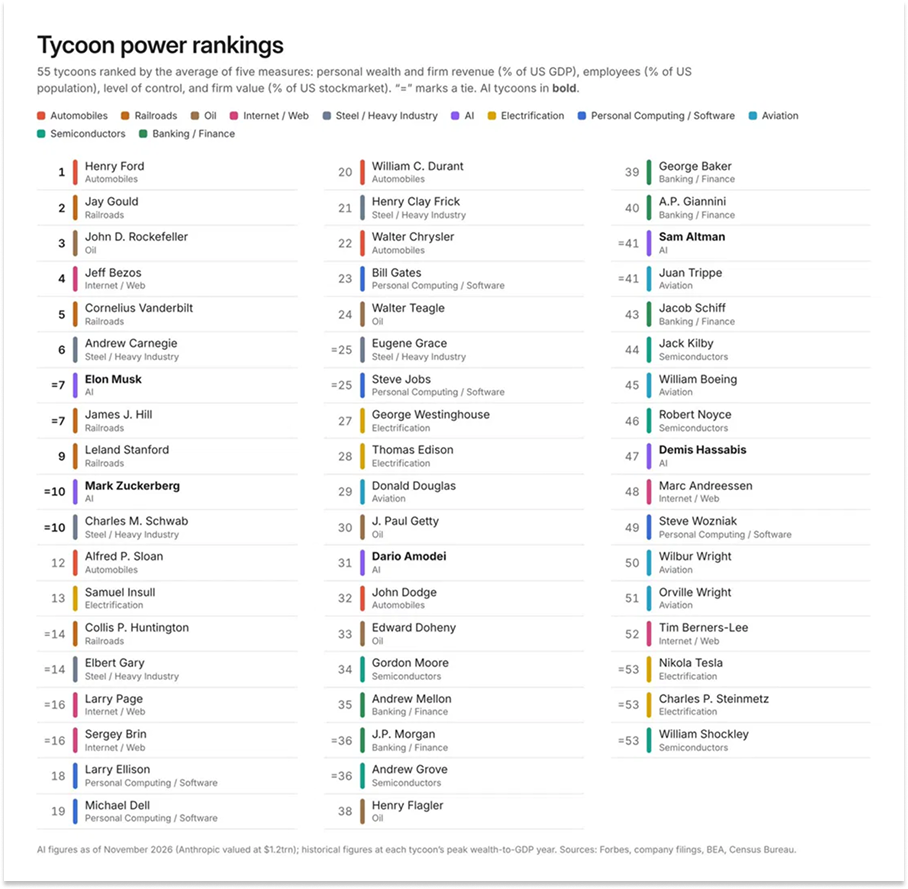
Coincidentally, after writing this, I saw a tweet with The Economist’s Tycoon Power Rankings, and the leaders are exactly who this piece would predict: those Industrial Age businessmen who consolidated after the busts and created cost leaders, a Vertical Integrator in a non-obvious market (Musk), and people like Zuck, Bezos, and Sergey & Larry who took advantage of abundant internet fiber. The Wrights come in considerably lower, at 50 and 51, respectively.
And as for the Anthropic IPO, and the AI bubble more broadly? No fucking idea.
In AI itself, and in categories beyond, AI may simultaneously accelerate imitation and the accumulation of advantage. No matter how futuristic the technology in question, it is the presence or absence of durable competitive advantage that determines whether a business and its investors will profit from its proliferation. That, and the price you pay to get in.
The more miraculous your technology, the more crucial your moats.
That’s all for today. We’ll be back in your inbox Friday with a Weekly Dose.
Thanks for reading,
Packy